Life Insurance & Retirement: Family Planning Tips
Personal Finance, Life Insurance, Retirement Planning
Life Insurance and Retirement Planning: What Families Should Know
Building a secure future is about more than earning a paycheck. It requires thoughtful financial planning that balances today’s needs with tomorrow’s goals. For most families, that means coordinating life insurance, retirement planning, and long‑term retirement savings so loved ones are protected no matter what happens.
Why Life Insurance Belongs in Your Long-Term Plan
Many people think of life insurance only as a payout after death, but it is actually a cornerstone of family financial security. At its core, life insurance replaces income that would be lost if a breadwinner passes away, helping your family stay in the home they love, keep up with everyday bills, and continue important goals like college or retirement for a surviving spouse.
There are two broad types of coverage most families consider:
Term life insurance, which covers you for a set period (for example, 20 or 30 years) and is often the most affordable way to protect young families during high‑expense years.
Permanent life insurance, which can last your entire life and may build cash value that you can access while living, adding flexibility to your overall financial planning.
The key is matching coverage to your family’s needs: debts, childcare, education costs, and the income your household would need to stay afloat. Properly structured, the insurance benefits from a policy can act as a financial safety net just when your loved ones need it most.
Connecting Life Insurance and Retirement Planning
Retirement planning is about ensuring you have enough income to maintain your lifestyle once paychecks stop. That typically involves building retirement savings in accounts like 401(k)s, IRAs, or pensions. Where does life insurance fit in? It supports your plan at every stage.
During working years: Life insurance can protect your spouse’s future retirement by replacing the savings you would have contributed if you were still alive.
As you approach retirement: Coverage can help pay off remaining debts, such as a mortgage, so fewer retirement dollars are tied up in monthly payments.
In retirement itself: Some people use policies to leave a legacy for children or grandchildren, allowing them to spend more of their own nest egg without worrying about what is left behind.
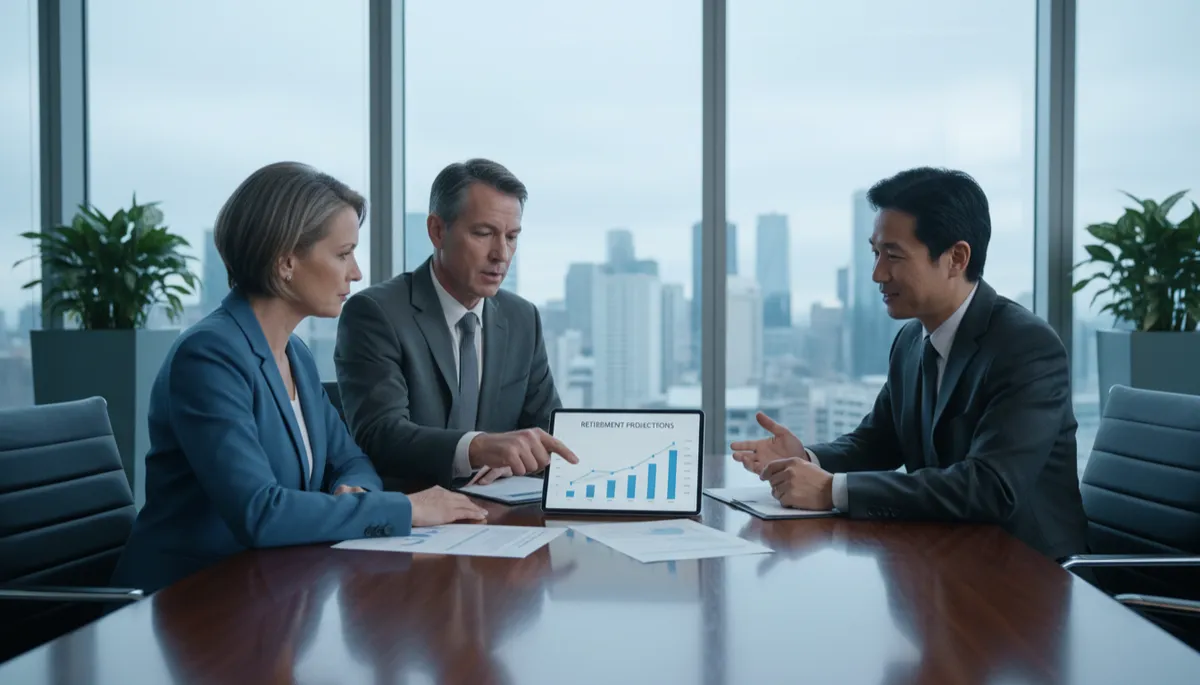
Coordinating insurance and investments helps families turn goals into a clear retirement roadmap.
Building Strong Retirement Savings for Your Family’s Future
A solid retirement savings strategy starts with understanding how much income you will need later in life. A common rule of thumb is to aim for replacing 70–80% of your pre‑retirement income, though your needs may be higher or lower depending on lifestyle, healthcare costs, and whether you plan to work part‑time.
Take advantage of employer retirement plans, especially matching contributions, which are essentially free money toward your future.
Consider IRAs or other tax‑advantaged accounts to supplement workplace plans and diversify your sources of income in retirement.
Automate contributions so saving becomes a habit, not an occasional decision that can be postponed.
💡 Pro Tip: Review your retirement planning at least once a year. Life changes—such as a new baby, a home purchase, or a job change—often mean adjusting both your savings rate and your life insurance coverage.
Understanding Insurance Benefits Beyond the Payout
The most obvious insurance benefit is the tax‑free death benefit paid to your beneficiaries. But modern policies can offer much more. Some permanent policies build cash value that grows over time and can be borrowed against for emergencies, education, or even to supplement income in later years. Others include riders that allow access to a portion of the benefit if you become seriously ill, providing a cushion during difficult times.
These features should never replace a dedicated retirement savings plan, but they can add flexibility to your overall financial planning strategy. The right mix of policies and accounts can help you manage risk while still pursuing growth.
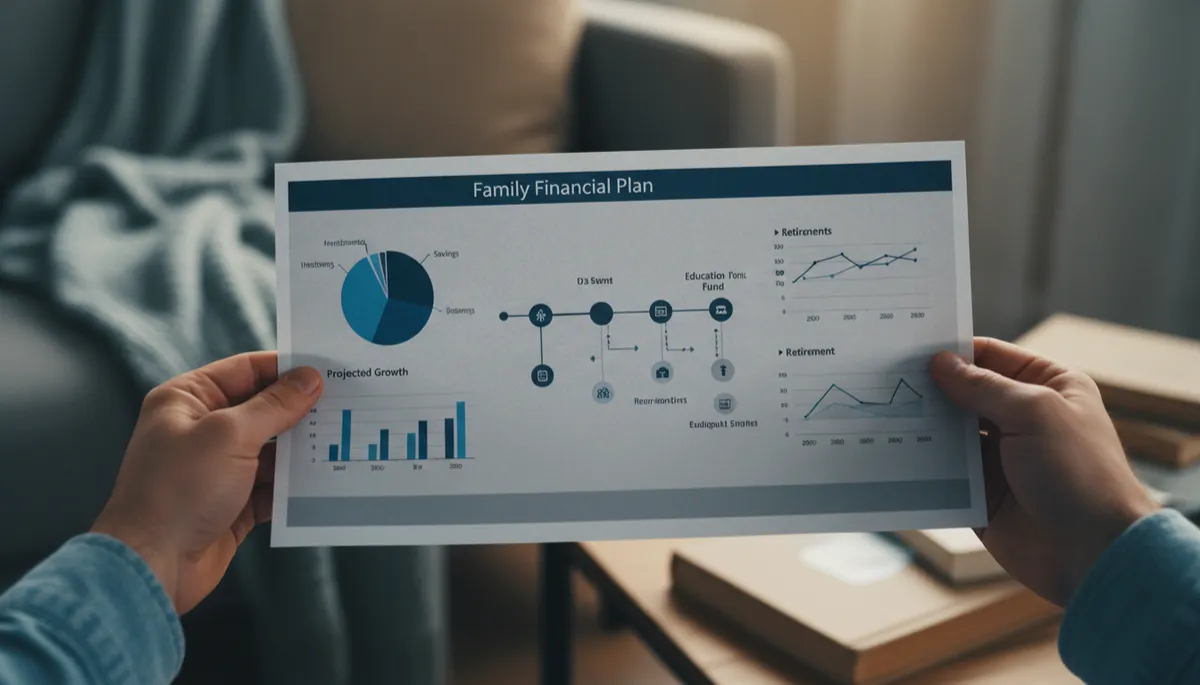
A written plan turns abstract goals like security and comfort into concrete financial steps.
Putting Family Financial Security at the Center
Ultimately, the purpose of life insurance, retirement planning, and disciplined retirement savings is the same: lasting family financial security. When you coordinate these pieces, you are not just buying products—you are creating a safety net and a roadmap that supports your family through every season of life.
Start by taking inventory of where you stand today: your income, debts, savings, and existing coverage. Then, define what you want the future to look like—when you hope to retire, the lifestyle you envision, and the support you want to leave for loved ones. With that vision in mind, a trusted financial professional can help you align financial planning, insurance benefits, and investments into one clear strategy.
You do not need to have everything figured out at once. Small, consistent steps—such as increasing your retirement contributions, updating your life insurance, or creating a written budget—can dramatically change your family’s trajectory over time. The most important move is simply to begin, so that the people you care about most are protected today and prepared for tomorrow.
Contact Us: