Protect Families, Build Your Career, Make a Difference
TPI Agency leverages technology to provide life insurance agents with the ultimate platform, training, and resources needed to excel in the industry.

Succeed Financially
By Making the Right Choices
TPI strives to empower underserved communities in America by providing financial education and protecting their family legacies through life insurance.
At the same time, our opportunity enables agents to make a difference while earning income and creating a flexible business for long-term financial security.
TPI Offers Both Life Insurance and
a Lasting Career
Step-by-Step Training & Mentorship
We guide you from day one — no experience or license required. Learn the business, master the products, and grow your skills with personalized support from successful field trainers.
Flexible, Remote Income Opportunity
Build your own schedule, work from anywhere, and earn what you’re worth. Whether you want part-time freedom or full-time entrepreneurship, we give you the tools to thrive.
Cutting-Edge Digital Tools
Use our powerful CRM, automation systems, and a full Canva content hub to grow your business fast — online or in the field.
Leadership & Business Ownership Path
With TPI, you're not just selling — you're building. Scale your own agency, earn override commissions, and take control of your future.
People of Different Paths
United As One
As part of our fundamental values and commitment to representing America’s rich diversity, TPI welcomes individuals from all walks of life, providing them with an equal opportunity to excel as licensed life insurance agents.
Making Life Insurance Truly Come Alive
TPI Opportunity
TPI Celebrates Entrepreneurship
TPI Agency Joins Integrity
Our Latest Blogs
Integrating Life Insurance in Retirement Planning
Life Insurance, Retirement Planning, Wealth Management, Financial Security
How Life Insurance Fits Into a Long-Term Retirement and Wealth Plan
Life Insurance is often seen purely as protection against the unexpected, but it can also be a powerful tool in Retirement Planning and long-term Wealth Management. When used strategically, the Insurance Benefits go far beyond a death benefit, supporting Financial Security, tax efficiency, and legacy goals throughout your life.
Life Insurance as the Foundation of Financial Security
At its core, Life Insurance provides a tax-free lump sum to your beneficiaries if you pass away. This safety net protects your family’s Financial Security by replacing lost income, paying off debts, and covering major expenses such as education or a mortgage. In a long-term Retirement Planning context, this protection allows you to take calculated investment risks, knowing your loved ones are shielded if something happens to you earlier than expected.
Without adequate coverage, your retirement and Wealth Management strategy can quickly unravel. Survivors may be forced to liquidate Long-term Investments at the wrong time, sell property at a discount, or abandon important goals. A properly structured policy acts as a financial backstop, preserving the integrity of your broader plan even under stress.
💡 Pro Tip: Review your Life Insurance coverage whenever you experience a major life event—marriage, children, a new home, or a big promotion—to keep your Financial Security in step with your responsibilities.
Term vs. Permanent: Matching Insurance to Your Retirement Timeline
A key Wealth Management decision is choosing between term and permanent Life Insurance—or a blend of both. Term insurance offers affordable protection for a specific period, such as 20 or 30 years. It’s ideal for covering high-risk years when you are building Long-term Investments, paying off a mortgage, or raising children. If your goal is pure Financial Security during your working years, term can be a cost-effective solution that frees more cash for retirement savings.
Permanent policies, such as whole life or universal life, can stay in force for your entire lifetime, as long as premiums are paid. These policies often include a cash value component that grows over time. For some, this creates an additional Long-term Investment bucket that can complement traditional retirement accounts, offering Insurance Benefits like tax-deferred growth and potential access to funds through loans or withdrawals.
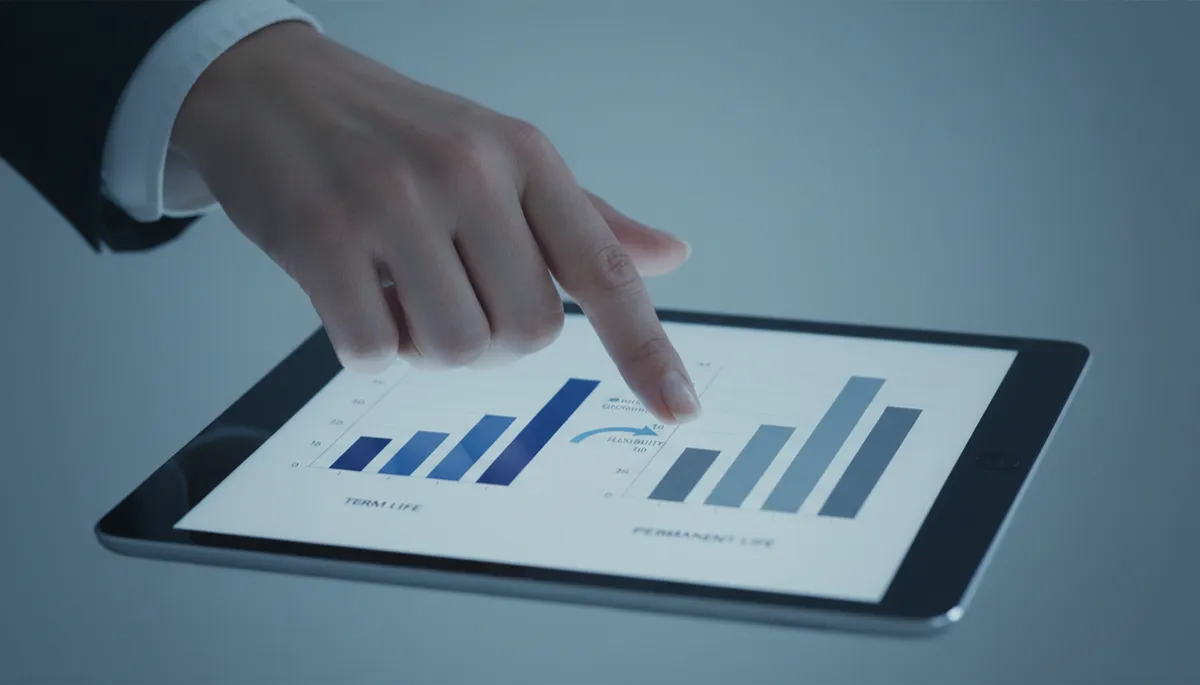
Aligning term and permanent coverage with life stages can optimize protection and cost.
Cash Value and Long-Term Investments Within a Policy
For individuals focused on Retirement Planning and Wealth Management, the cash value in permanent Life Insurance can play several roles. Over time, this value may grow at a guaranteed rate, a rate linked to market performance, or a combination of both, depending on the policy type. While it should not replace dedicated retirement accounts, it can add diversification and stability to your Long-term Investments.
In retirement, some policyholders choose to access cash value to supplement income, bridge market downturns, or fund one-time expenses such as medical care or home renovations. Because loans from a policy are typically not taxable if managed correctly, this can be a flexible source of funds that supports ongoing Financial Security. However, borrowing too aggressively can reduce the death benefit and jeopardize Insurance Benefits, so it’s essential to coordinate this strategy with a financial professional.
Tax Advantages, Estate Planning, and Legacy Goals
Thoughtful Wealth Management goes beyond your own retirement income; it also considers what you leave behind. Life Insurance death benefits are generally income tax-free to beneficiaries, which makes them a powerful estate planning tool. They can provide heirs with immediate liquidity to cover estate taxes, settle debts, or equalize inheritances when some assets—such as a business or property—are difficult to divide.
For those with charitable goals, Life Insurance can also amplify your giving. Naming a charity as a beneficiary or using a policy inside a trust can create a meaningful legacy, often at a lower cost than donating the same amount from other Long-term Investments. In this way, Insurance Benefits extend beyond protection, helping you shape how your Wealth Management decisions impact future generations and causes you care about.
Integrating life insurance into estate plans can protect heirs and preserve assets.
Integrating Life Insurance Into a Comprehensive Wealth Plan
The most effective Retirement Planning strategies treat Life Insurance as one component of a broader Financial Security framework, not a standalone product. Start by clarifying your goals: How much income will you need in retirement? What debts must be covered? How important is leaving a legacy? Then, coordinate your insurance coverage with savings accounts, employer retirement plans, IRAs, brokerage portfolios, and real estate holdings.
A financial advisor or wealth manager can help you evaluate different Insurance Benefits, compare policy types, and determine appropriate coverage levels. They can also stress-test your plan against scenarios such as market downturns, health events, or early death, showing how Life Insurance can stabilize outcomes. This integrated approach to Wealth Management helps ensure that your Long-term Investments, protection strategies, and retirement income sources all work together toward the same objective: lasting Financial Security for you and those you love.
Ultimately, Life Insurance is not just about what happens when you are gone. When thoughtfully woven into your Retirement Planning and Wealth Management strategy, it supports your financial life at every stage—protecting your family today, expanding your options tomorrow, and preserving your legacy for the future.
Contact Us:


Copyright 2025 TPI Agency. All rights reserved.